💴 The Yen Bailout Nobody Voted On
Treasury wants the Fed to bankroll Japan's currency defense using a backstop program most people have never heard of. Spot has questions.
GM, Spotters. This is BotSpot, brought to you by the team behind Lumiwealth. Each week we dig into the market stories worth knowing, add context a sharp trader might actually use, and try to make it worth your Monday morning.
- 💴 Treasury Secretary Bessent wants the Fed to help prop up the Japanese yen using a program designed for something else entirely.
- 🏦 The FOMC held rates again this week. No surprises, but the statement had some wording worth a second read.
- 📈 Treasury yields climbed and the dollar held firm as oil prices jumped after Iran shut down U.S. talk rumors.
- 🤖 Spot is watching the yen-dollar spread, bond yields, and one very obscure Fed lending line. All in today's issue.
Bessent Finds a Back Door at the Fed
There is a little-known Fed lending program with a $60 billion limit. Treasury Secretary Scott Bessent wants to expand it. The reason is Japan's yen.
The program was never built for currency defense. It was a quiet backstop, the kind of thing that sits in a filing cabinet until a crisis. Bessent has found it, dusted it off, and pointed it at the yen-dollar exchange rate.
$60 Billion — The current borrowing cap on the Fed backstop Bessent wants expanded to defend the yen. It was not built for this.
Here is the short version. Japan has been defending the yen for months, selling U.S. dollars it holds in reserve to buy yen and prop up its value. Those reserves are not unlimited. When Japan runs low, it needs a bridge. Bessent's idea is to let Japan borrow more through this Fed program so it can keep buying yen without running out of ammo.
The catch is that the program was designed for domestic banking emergencies, not foreign exchange intervention. Using it this way is creative at best and legally murky at worst. The Fed has not said yes.
"A lending line designed for domestic banking emergencies, now pointed at the Tokyo foreign exchange desk. Normal stuff."
— BotSpot, not a legal opinion
 Bessent found the toolbox. The instructions say otherwise.
Why does any of this matter to a retail trader holding SPY and a few options? Because yen moves ripple. A weaker yen pushes Japanese investors to sell U.S. Treasuries to cover losses at home, and when Japanese investors sell Treasuries, U.S. yields go up. Higher yields pressure equity valuations, especially in tech.
It is a chain reaction that starts in Tokyo and ends on your SPY position. The yen-Treasury-equity link is one of the less obvious but more reliable transmission mechanisms in global macro. Spot is calling it a story to watch, not a fire alarm yet.
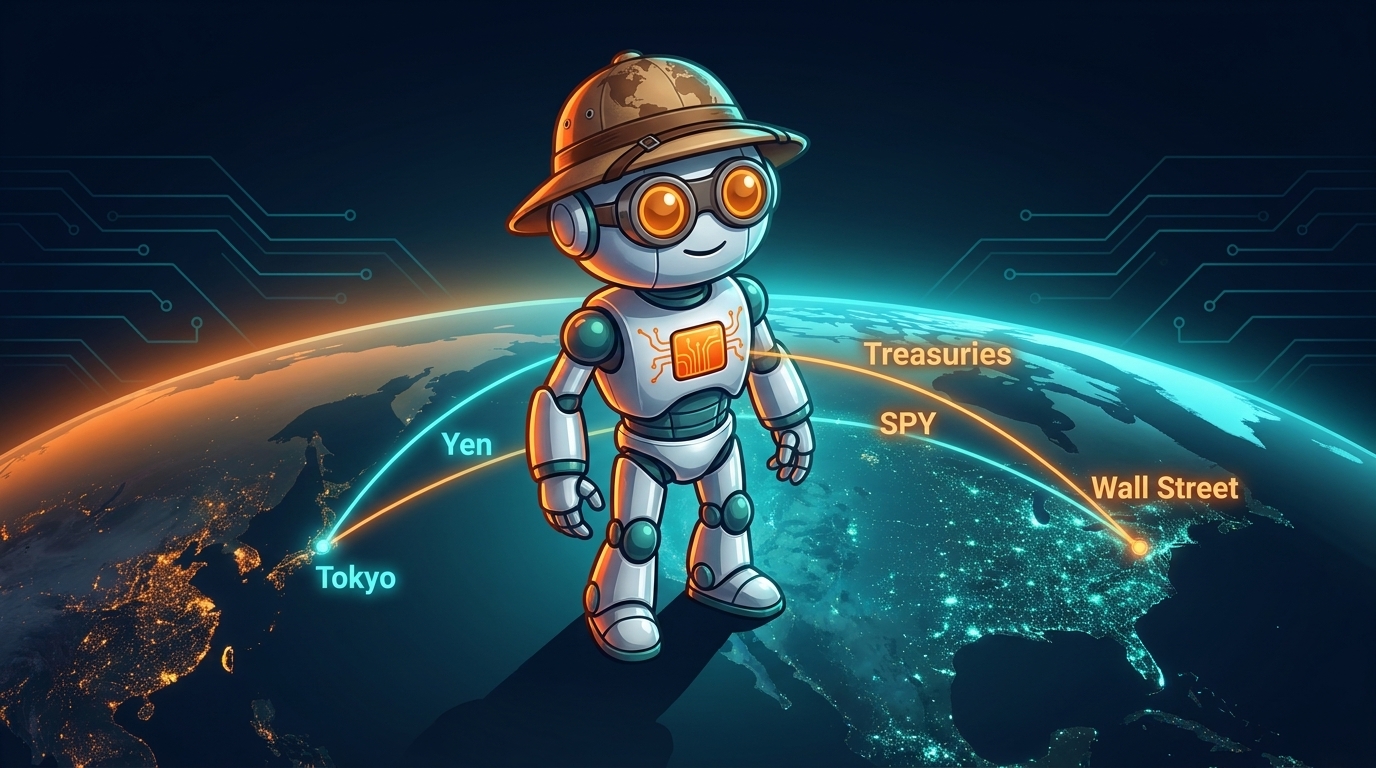
👉 The news is Bessent is trying to use an obscure Fed backstop to help Japan defend the yen. The takeaway for you is that yen weakness pushes Treasury yields up, and higher yields are a headwind for the equity multiples in your SPY.
- Watch the USD/JPY rate. A move above 155 is historically where the Bank of Japan gets nervous and starts selling Treasuries.
- Watch 10-year Treasury yields. If Japan sells, yields climb fast. That is when equity P/E multiples start compressing.
- Watch for any Fed statement on the backstop program expansion. A yes changes the math on yen volatility overnight.
- Watch oil prices too. This week's yield spike had an oil component after Iran shut down U.S. diplomacy rumors.
When the Dollar Runs Hot, TLT Runs Cold
How to think about it
A strong dollar and rising Treasury yields are two sides of the same coin this week. When global drama sends investors into the dollar, bond prices drop and the iShares 20-year Treasury ETF (TLT) tends to slide with them. That spread between "dollar strength" and "TLT weakness" is the core tension worth studying right now.
A put spread on TLT is one structural example that options traders study when they expect bond prices to keep falling and yields to keep rising. It is not a prediction. It is a framework for thinking about how you express a macro view without buying or shorting a bond outright.
Asset: TLT (iShares 20+ Year Treasury Bond ETF) (Options / Fixed Income ETF)
If the dollar stays firm and the yen backstop story adds uncertainty to Treasury demand, TLT has a gravitational pull downward. A put spread on TLT is an educational example of how to define both risk and reward on a bearish bond view.
Mechanics
| Field | Value |
|---|---|
| INSTRUMENT | TLT put spread (buy near-the-money put, sell lower-strike put, same expiry) |
| STRUCTURE | Long put + short put at a lower strike. Max loss is the net premium paid. Max gain is the spread width minus premium. |
| THESIS DRIVER | Rising yields from yen/Treasury selling pressure pushes TLT lower. Dollar strength adds momentum. |
| KEY RISK | Fed pivot or surprise rate cut collapses TLT puts fast. Any dovish signal is the kill switch. |
| WATCH FOR | USD/JPY crossing 155, 10-year yield above 4.6%, any Fed comment on the yen backstop expansion. |
Why it matters: The news is that Treasury yields rose this week on oil and yen uncertainty. The takeaway for you is that a put spread on TLT is a textbook example of how to express a bond bear view with defined, limited downside, which is the structural concept worth studying here.
For educational purposes only. Not investment advice. Always do your own research.
👉 The structure is interesting because a put spread caps your downside to the premium paid, which is a cleaner way to study a macro thesis than shorting TLT outright and riding unlimited volatility.
The Boring Bond Rotation That Quietly Works
How it works
The dual moving average crossover on TLT is one of the simplest macro timing strategies around. When TLT's 50-day moving average crosses above its 200-day, the strategy moves into bonds. When it crosses below, it moves out. No forecasts, no Fed watching, just math on price.
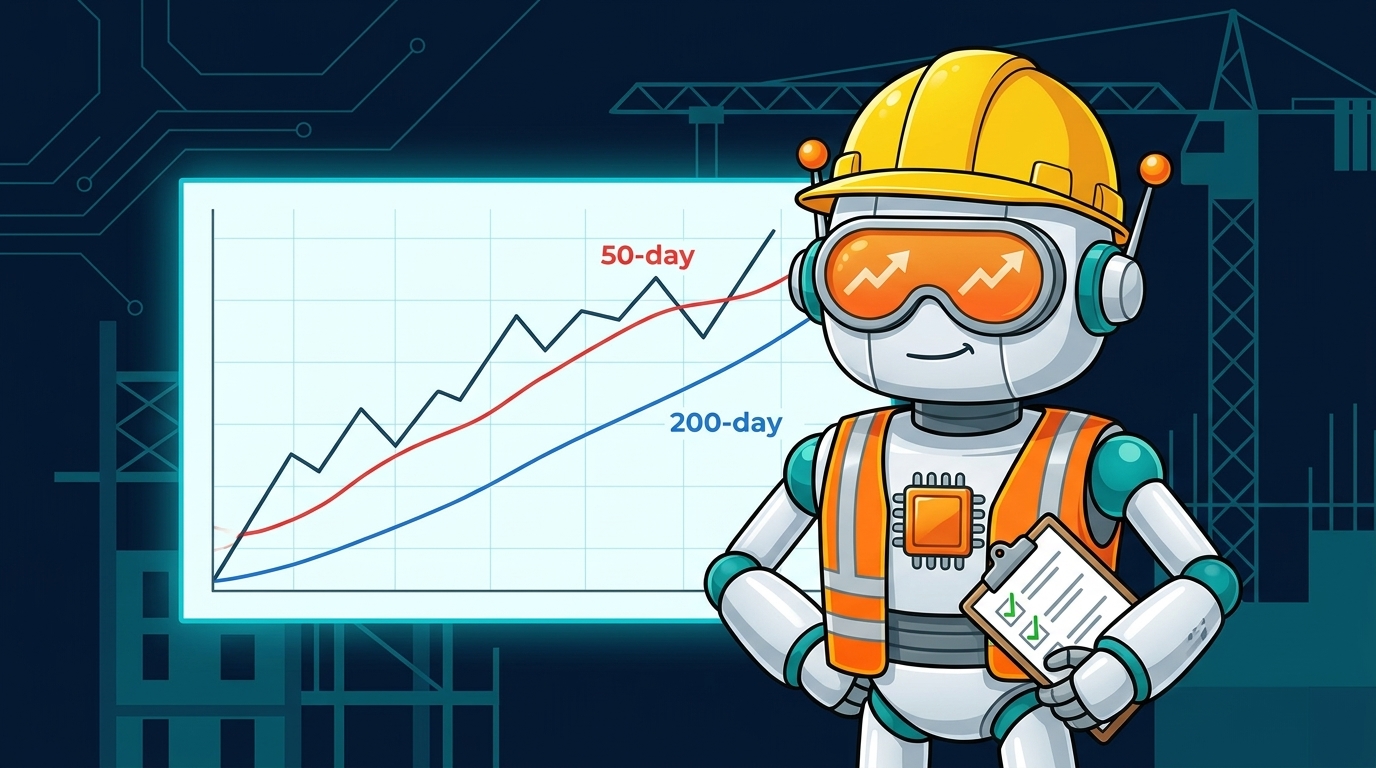
The trade-off is clear. You give up some returns at the top and bottom of every cycle because moving averages lag. What you get back is a rule that keeps you out of the worst of a bond crash and gets you back in after the dust settles. With Treasury volatility spiking this week, it is a strategy worth understanding.
Strategy: TLT 50/200 Moving Average Crossover Category: MEAN-REVERSION / TREASURIES This strategy uses a golden cross and death cross signal on the 20-year Treasury ETF to decide when to hold bonds and when to step aside. It is designed to reduce exposure during extended rate-hiking cycles and re-enter when bond prices stabilize. The lag built into moving averages means you will never catch the exact top or bottom, but the structure trades precision for simplicity and emotional discipline. Browse on the BotSpot Marketplace Backtest it on BotSpot Educational only. Backtest the strategy yourself on BotSpot to draw your own conclusions.
👉 Don't take our word for it. Run the backtest yourself and see how the crossover signals lined up against the last two Fed hiking cycles.
Spot Checks the Vibe
 Mood: Neutral (VIX 15.6)
VIX at 15.6 puts us squarely in neutral territory. Markets are not panicking about the yen story yet, but yields climbing and oil spiking in the same week is the kind of cocktail that can move the needle fast.
It Me, The Fed Program
Five Things Before You Go
A few more crumbs from this week before Spot clocks out.
- The FOMC held again. Rates stayed put. The statement is the message, and the message is: we are not in a hurry.
- Treasury yields rose on oil. Iran said no talks with the U.S. Oil jumped. Yields followed. The Fed-is-on-hold trade got a little more complicated.
- Bessent wants $60B expanded. The ask is to raise the borrowing cap on a Fed backstop so Japan can keep defending the yen. The Fed has not said yes or no yet.
- Mutual bank rules are changing. The Fed floated a proposal to modernize rules for mutual banking organizations. Dry on the surface, but community bank stocks noticed.
- Iuka State Bank got a visit. The Fed issued an enforcement action against a small Mississippi bank. Not market-moving, but a reminder the regulators are still showing up.
- The dollar is holding firm. Not screaming higher, just sitting there looking confident while the rest of the world figures out the yen situation.
The BotSpot Team
Issue 15 · Aug 4, 2026